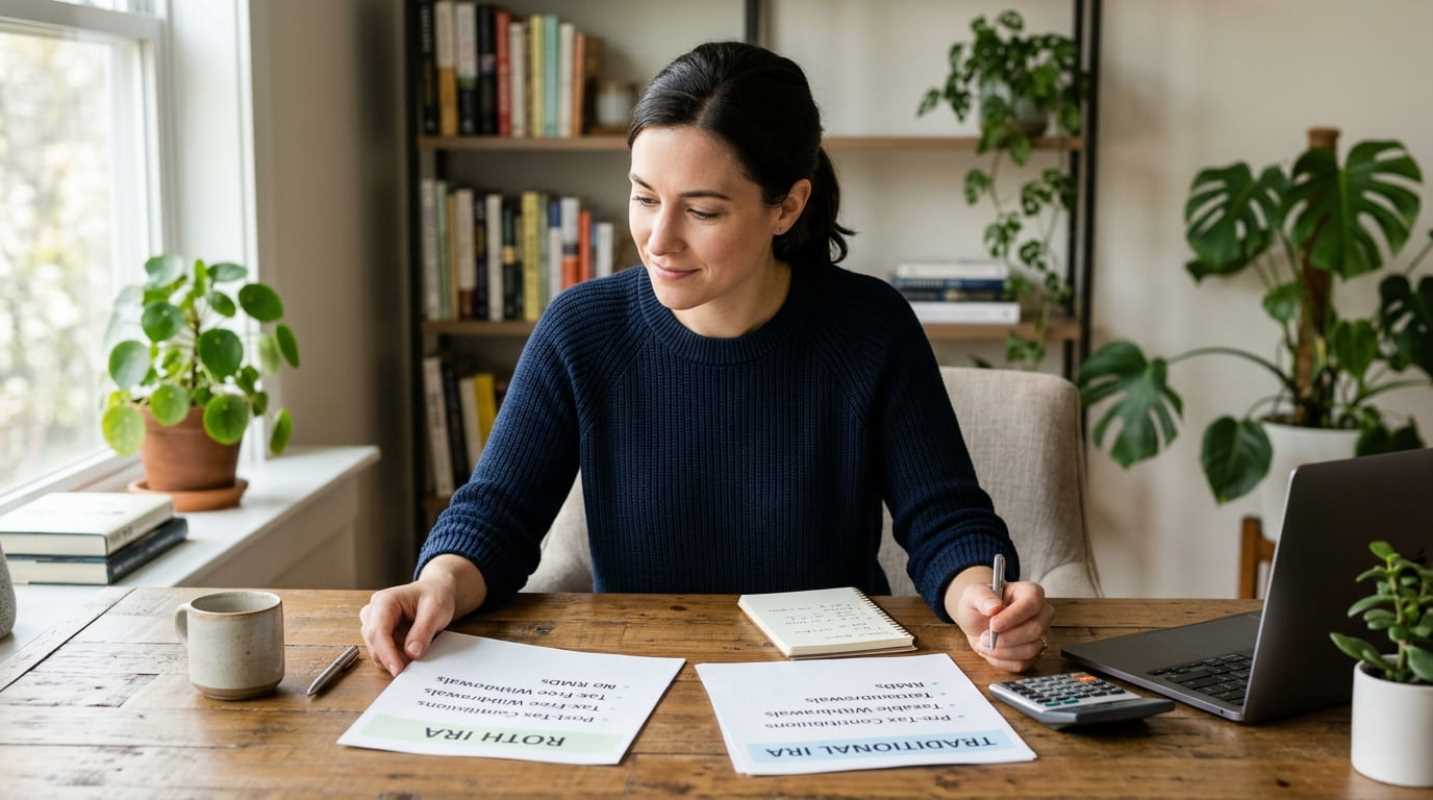
Picking a retirement account often feels like trying to read a map written in another language. You hear people tossing around terms like pre-tax, post-tax, deductions, and distributions, and your eyes glaze over. Have you been there? Most people have.
Beneath the financial jargon, the whole decision comes down to one simple question: do you want to pay taxes right now, or would you rather pay them later?
That single question is the fork in the road between a Traditional IRA and a Roth IRA. Neither account is universally better than the other. Instead, the right choice depends on where you stand financially today and where you plan to be down the road. Once you understand how these two accounts treat your money, choosing between them becomes straightforward.
Tax-Free vs Tax-Deferred Growth Mechanics
The Traditional IRA is built on the concept of tax-deferred growth. When you put money into a Traditional IRA, you can often deduct that contribution on your tax return for that year. That lowers your taxable income right away. Your investments grow inside the account without annual tax bills on dividends or capital gains. The bill comes later. When you withdraw the money in retirement, every dollar gets taxed as ordinary income at whatever your tax rate is at that time.
A Roth IRA turns that equation on its head. You contribute money you have already paid taxes on, so there is no tax break today. In exchange, your money grows completely tax-free. When you take qualified withdrawals in retirement, you do not owe the IRS a single penny.
To see why this matters, look at two different savers.
Alex is 25, working an entry-level job, and sits in the 12% federal tax bracket. Alex contributes $7,000 to a Roth IRA, paying about $840 in upfront taxes. Over 35 years, assuming a 7% average annual return, that single contribution grows to nearly $75,000. When Alex retires, that entire $75,000 is tax-free. Giving up an $840 deduction in exchange for avoiding taxes on $67,000 of growth is a huge win.
Now consider Morgan, who is 48 and in peak earning years. Morgan sits in the 32% federal tax bracket and lacks an employer retirement plan. Contributing $7,000 to a Traditional IRA gives Morgan an immediate tax savings of over $2,200 today. If Morgan's income drops to a much lower tax bracket in retirement, paying taxes later at 12% or 22% beats paying 32% today. That difference in tax brackets is where you win.
Income and Contribution Limits
The IRS does not let you stash unlimited amounts into these accounts. For both Traditional and Roth IRAs, the combined annual limit is $7,000 for savers under age 50, and $8,000 for those age 50 and older.¹ You also must have earned income at least equal to your total contribution.
Although anyone with earned income can open and fund a Traditional IRA, your ability to deduct that contribution depends on your income and workplace access. If you participate in a workplace plan like a 401(k), full deductibility in 2025 and 2026 phases out for single filers earning between $79,000 and $89,000.¹ For married couples filing jointly, that phase-out range sits between $126,000 and $146,000.¹ If you make more than that, you can still contribute, but you get no upfront tax deduction.
Roth IRAs carry hard income ceilings on who can contribute directly. For single tax filers, the ability to contribute phases out between $150,000 and $165,000 of modified adjusted gross income.¹ For married couples filing jointly, the phase-out range runs from $236,000 to $246,000.¹ Earn a dollar above the top of those bands, and you cannot put money directly into a Roth IRA.
High earners do have a workaround called the backdoor Roth IRA. You simply deposit money into a non-deductible Traditional IRA and then convert those funds into a Roth IRA. Keep in mind that the IRS enforces the pro-rata rule here. If you hold existing pre-tax balances in other Traditional IRAs, the IRS treats the conversion as a mix of taxable and non-taxable funds, which could trigger a tax bill.
Your Retirement Timeline and Flexibility
Your time horizon changes how much value you get out of each account. Compound interest is quiet in the early years, but it turns into a runaway train over three or four decades.
Because compound growth creates a mountain of investment earnings over time, younger savers get far more mileage from a Roth IRA. In a Roth, every cent of that compound growth avoids taxation forever. If you have only five or ten years left until retirement, the tax break on contributions from a Traditional IRA might save you more actual cash than a decade of tax-free growth would.
Liquidity is another area where the Roth IRA stands apart. Life happens, and sometimes you need cash. With a Traditional IRA, taking money out before age 59½ usually triggers ordinary income taxes plus a stiff 10% penalty.
A Roth IRA works differently. Because you already paid taxes on your original deposits, you can withdraw your direct contributions at any time, for any reason, with zero taxes and zero penalties.² Your earnings must stay untouched until age 59½ to remain tax-free, but having access to your principal offers real peace of mind.
Rules around mandatory withdrawals also separate the two accounts. With a Traditional IRA, the government requires you to start pulling out money through Required Minimum Distributions (RMDs) once you reach age 73.³ That forces you to realize taxable income whether you need the money or not. A Roth IRA has no lifetime RMDs for the original owner. Your money can sit and compound indefinitely, making it a great tool if you plan to leave wealth behind for your family.
Making the Final Decision on Your Retirement Account
So what does this actually mean for your wallet? You do not need a finance degree to pick the right path. Run through this quick checklist to see which bucket matches your current situation
• Choose a Traditional IRA: You are in your peak earning years and pay a high marginal tax rate today. Taking the upfront deduction gives you immediate relief. It also makes sense if you expect your expenses and income to fall sharply once you retire.
• Choose a Roth IRA: You are early in your career, earning a modest salary, or currently sit in the 10% or 12% tax bracket. Locking in low taxes today gives you decades of tax-free growth. It also fits if you want an emergency backup pool or want to avoid forced RMDs down the line.
Remember that you do not have to pick just one forever. Many people use a hybrid approach. You can fund a Roth IRA while simultaneously contributing pre-tax dollars to a workplace 401(k). Having both gives you tax flexibility in retirement, allowing you to pull money from whichever account keeps you in the lowest possible tax bracket each year.
The worst move you can make is waiting for absolute certainty. Pick the account that matches your life right now, put your money to work, and let time handle the heavy lifting.
Sources:
1. IRS Announces 2025 Retirement Plan Dollar Limits and Thresholds
https://tax.thomsonreuters.com/news/irs-announces-2025-retirement-plan-dollar-limits-and-thresholds/
2. Roth vs. Traditional IRA
https://investor.vanguard.com/investor-resources-education/iras/roth-vs-traditional-ira
3. Retirement Topics: IRA Contribution Limits
https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-ira-contribution-limits
*This article on Katiently is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*
 Basics- How to Get the Full Employer Match -2.jpg)