Think about the last time you bought groceries or paid for coffee. You probably tapped your phone against a terminal or swiped a piece of plastic. For your kids, that plastic card looks like magic. You tap it, and things appear.
This invisible money effect creates a real puzzle. Children today rarely see paper bills change hands. Over 65% of Generation Alpha kids spend hours inside games like Roblox, trading virtual currencies, before they have ever counted out change at a physical checkout counter. Money has turned into floating pixels.
Research from Child Trends and T. Rowe Price shows that while 87% of parents talk to their children about money, 57% still feel nervous discussing family finances, debt, and paychecks.¹ You might worry about burdening them with adult stress. That hesitation makes sense, but total silence does not protect your kids. It just leaves them to figure out money through social media influencers and mobile game stores.
The good news is that you do not need an economics degree to guide your kids. You simply need to treat money as an everyday practical tool. When you talk openly about costs and trade-offs, you demystify cash and give your kids the confidence they need in an increasingly cashless world.
Early Childhood Ages 3 to 6 Making Money Tangible
Research from the University of Cambridge shows that children form their core financial habits by age 7. That includes their instincts around patience, planning, and delayed gratification. If your child is in preschool or kindergarten, your goal is simple: make money visible, physical, and real.
Skip the traditional ceramic piggy bank. When kids drop coins into an opaque pig, the money disappears into a black hole. Use a clear glass jar instead. Watching a stack of quarters slowly rise in a clear jar teaches kids that savings accumulate one piece at a time.
Try these concrete activities with young kids
• Tactile Coin Sorting: Turn pocket change into a weekend matching game. Trace circles on paper for pennies, nickels, dimes, and quarters. Have your child match the coins to the shapes while you explain that smaller coins like dimes can actually be worth more than larger nickels.
• Checkout Conversations: When you pay at the grocery store, narrate the transaction. Say something direct: "We give our money to the cashier, and the store lets us take the groceries home." Let your child hand the physical cash to the cashier.
• Patience Practice: Practice delayed gratification at home with snacks or small toys. You might tell them, "You can have one strawberry right now, or if you wait until we unload the grocery bags, you can have three." Learning that waiting brings a bigger reward builds the mental muscle they need for long-term saving.
Elementary Years, Ages 7 to 12: Mastering Allowances and Saving
Once kids enter elementary school, basic arithmetic turns into practical decision-making. This is the age to introduce an allowance.
In their books on raising financially savvy kids, authors Ron Lieber and Beth Kobliner recommend separating basic chores from pocket money.² Cleaning a bedroom or setting the dinner table is part of contributing to a household. If you tie basic chores directly to allowance, your child can simply decide to skip their chores whenever they feel like they have enough money.
Instead, provide a modest base allowance as an educational sandbox. A dependable rule of thumb is $0.50 to $1.00 per week for every year of age. If your child wants extra spending money, you can offer paid jobs for tasks that go beyond normal household responsibilities, like raking leaves or washing the car.
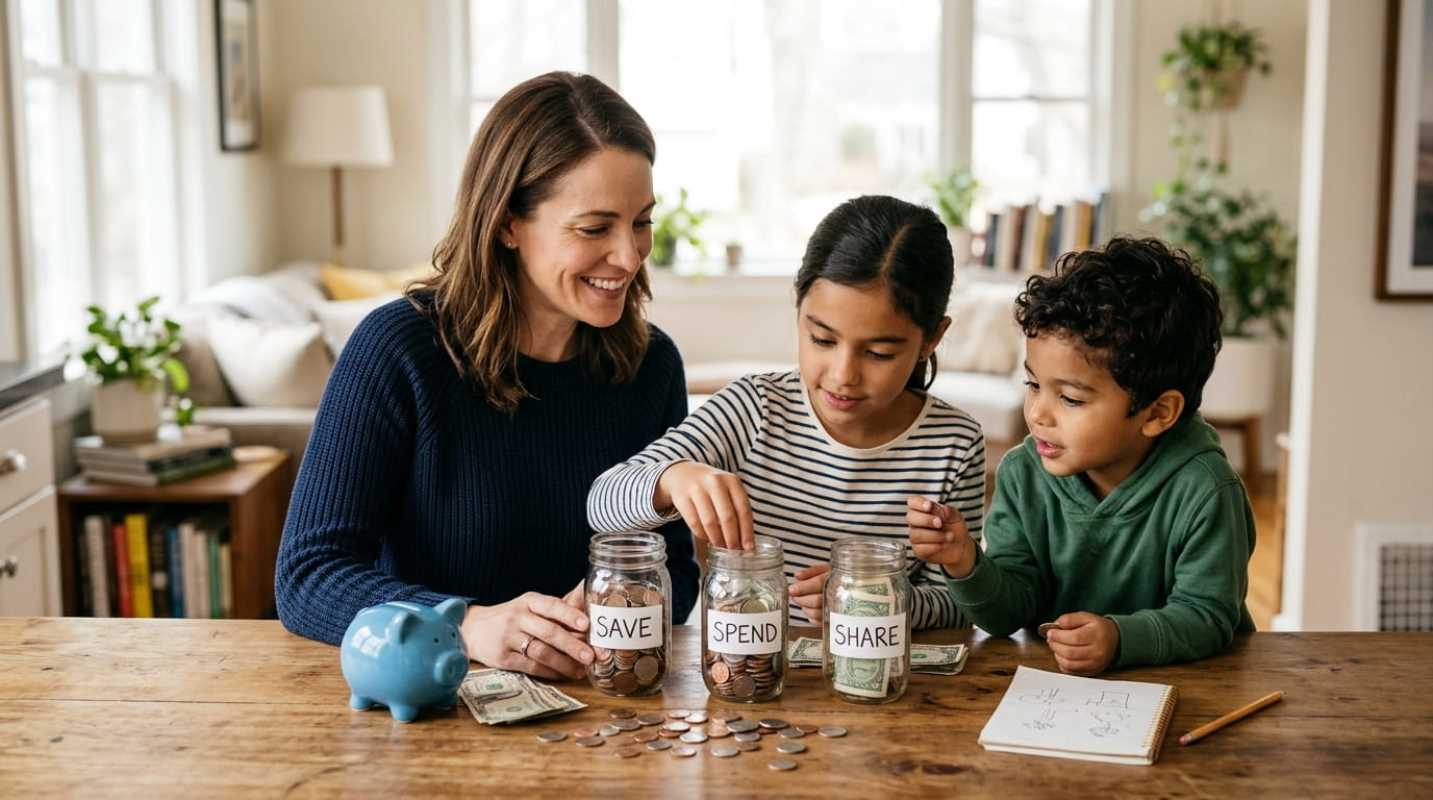
Set up a three-jar system: Spend, Save, and Give. A standard split is 70% for daily spending, 20% for savings goals, and 10% for charity or community gifts.
• Needs Versus Wants: Walk your child through everyday trade-offs. Ask them if an item is a need (something required for health, school, or safety) or a want (something fun to have). Let them debate the difference before buying.
• The Safe-to-Fail Sandbox: Let your kids make cheap mistakes right now. If your eight-year-old blows two weeks of allowance on a cheap plastic trinket that breaks an hour later, do not rush in to replace it. A child who regrets spending $10 at age eight avoids blowing $1,000 on an impulsive credit card purchase at age twenty.
• Virtual Currency Math: Gaming platforms hide the cost of virtual goods behind currencies like Robux and V-Bucks. Turn purchases into real-world math: "400 Robux costs $4.99. That is one full week of your allowance. Is this digital character skin worth seven days of waiting?"
• Compound Interest Demonstrations: Kids struggle to visualize bank interest. Create a home-bank match where you pay a 10% bonus on whatever remains in their "Save" jar on the last day of each month. Watching their money grow on its own makes compounding real.
The Teenage Years, Ages 13 to 18, and Real World Financial Responsibility
As teenagers grow more independent, classroom policy is catching up. The Council for Economic Education reports that 35 states require high school students to take a personal finance course for graduation.³ Although school classes help, the most valuable lessons still happen at home.
Teenagers need direct experience with digital accounts, taxes, and independent budgeting before they move out on their own.
• Transfer Discretionary Budgets: Stop buying all of your teen's clothes, streaming subscriptions, and social snacks piecemeal. Instead, calculate what you spend on those categories and transfer a set monthly budget into their account. If they spend their entire quarterly clothing budget on expensive sneakers, they wear their old shirts until the next budget cycle begins.
• Analyze Paychecks and Taxes: When your teen gets a first job, sit down with their initial pay stub. Explain why their take-home pay is lower than their hourly rate multiplied by their hours worked. Show them the specific deductions for federal taxes, state taxes, and FICA.
• Custodial Roth IRAs: If your teenager earns legitimate taxable income, open a custodial Roth IRA. Show them the math: contributing $1,000 at age 16, assuming an average 8% annual return without adding another cent, grows to more than $40,000 in tax-free retirement savings by age 65.
• Credit Basics and Scams: Add your older teen as an authorized user on your credit card to help them establish an early credit profile. Emphasize that credit cards are not free money; the full balance must be paid every single month to avoid high interest charges. Remind them to watch out for social media scams, fake sweepstakes, and peer-to-peer payment requests from strangers.
Building a Foundation for Lifetime Prosperity
You do not need to deliver a flawless financial lecture every weekend. Consistency and open discussion matter far more than perfection.
Start small today. Hand your preschooler the physical cash at the drive-thru window. Help your elementary student divide their birthday money into clear jars. Walk your teenager through your grocery receipt or their first paycheck.
When you give your kids the room to make modest choices, face natural trade-offs, and recover from small mistakes, you give them genuine financial independence. That confidence will stay with them long after they leave your kitchen table.
Sources:
1. Parents Talked to Kids About Money and Finances
https://www.childtrends.org/publications/parents-talked-kids-money-finances
2. Expert Advice on Kid Allowance
https://www.businessinsider.com/expert-advice-kid-allowance-2023-1
3. Survey of the States Show Progress for Financial Education
https://www.councilforeconed.org/2024-cee-survey-of-the-states-show-progress-for-financial-education/
*This article on Katiently is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*
 Basics- How to Get the Full Employer Match -2.jpg)