Saving up for your first home can feel like staring up at a sheer rock cliff. Between high rents and everyday expenses, putting aside tens of thousands of dollars sounds nearly impossible. Have you ever looked at local listing prices and wondered how normal people pull this off?
You are not alone, and you do not need to be rich to become a homeowner. The process simply comes down to breaking a big, intimidating number into a series of practical routines. Once you clear away the myths and put the right systems in place, your dream home shifts from a distant wish into a clear math problem you can solve.
The Reality Check and Setting Your Goal
Let's bust the single biggest myth in real estate right away: you do not need a 20% down payment.
For decades, buyers believed that anything less than one-fifth of the purchase price would get their mortgage application rejected. In reality, the median down payment for first-time buyers sits around 8% to 10%, according to recent findings from the National Association of Realtors.¹ First-time buyers now make up only about 22% of the market, and their median age has climbed to 40.¹ If you wait until you have saved 20%, you could spend years on the sidelines watching home values climb out of reach.
Minimum requirements are often much lower than people think. Conventional loans allow down payments as low as 3%, while standard FHA loans require 3.5%. On a $300,000 starter home, a 3.5% down payment is $10,500. That is a fraction of the $60,000 required for a traditional 20% down payment.
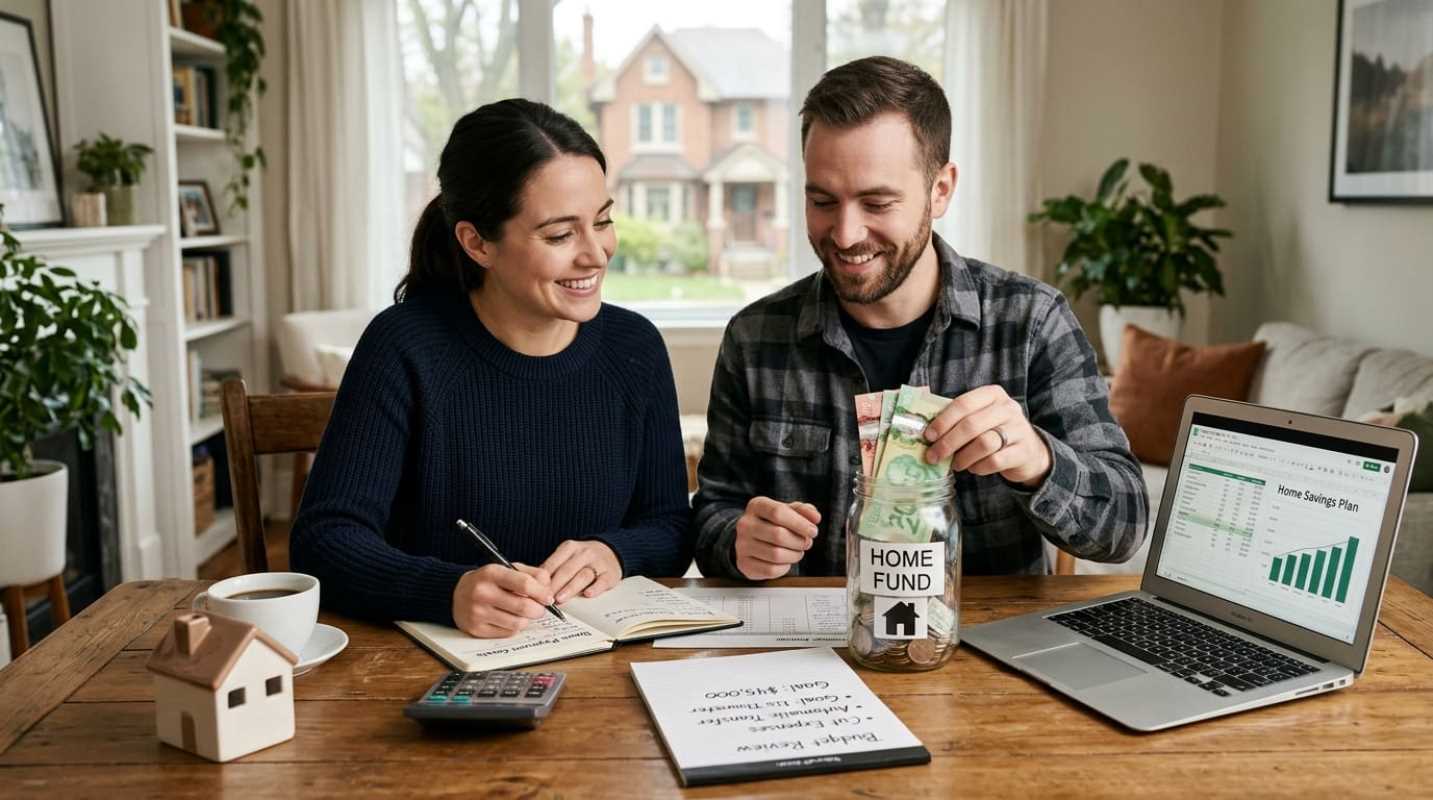
To set your actual target, look at starter home sale prices in your target neighborhoods. Pick an achievable down payment percentage, like 3.5% or 5%, and add an extra 3% to cover closing costs and moving fees. Divide that total dollar amount by the number of months you want to give yourself. If your target is $18,000 over two years, you need to save $750 each month. Seeing that specific number makes the path forward concrete.
Audit Your Finances and Cut the Fluff
Once you have a monthly target, you need to locate the cash to fund it. That starts with taking an honest look at where your money actually goes each week.
Print out your last three months of bank and credit card statements. Grab a highlighter and look for the slow leaks that drain your accounts without adding real value to your life. We all have them. It could be three streaming platforms you forgot you signed up for, gym memberships you stopped using in February, or pricey meal delivery fees. Cutting these expenses does not mean you have to give up all your fun. It just means choosing which goals matter most.
A reliable way to organize your income during this phase is the 50/30/20 budget framework
• Needs (50%): This covers your non-negotiables, including rent, utilities, basic groceries, transit, and minimum loan payments.
• Wants (30%): This bucket includes entertainment, dining out, hobbies, and shopping.
• Savings (20%): This portion goes directly toward your down payment fund and emergency savings.
If your income allows, consider trimming your wants down to 20% temporarily. Funneling that extra 10% straight into your home fund can shave months off your timeline.
Make Saving Effortless with Automation
If you wait to save whatever money remains at the end of the month, you will rarely save anything. Human nature takes over, and open checking account balances tend to disappear on routine impulse purchases.
The solution is to put your savings on autopilot. Set up a direct-deposit split with your employer's payroll system so that a flat dollar amount or a percentage of your pay moves into your home fund before it ever hits your checking account. When the money never touches your daily spending balance, you automatically adapt your lifestyle to what is left over.
Where you store this money matters just as much as how you collect it. Avoid parking your down payment cash in a traditional checking or savings account earning 0.01% interest. Instead, open a high-yield savings account (HYSA) paying 4% or more. On a $20,000 balance, the difference between a traditional bank rate and a high-yield rate can mean hundreds of dollars in risk-free interest each year.
Keep your high-yield savings account at a completely separate bank from your checking account. When it takes two to three business days to transfer money back to your debit card, you create a natural pause that stops you from raiding your house fund for weekend splurges. Treat that automated monthly savings transfer like an unavoidable utility bill.
Tap into First-Time Buyer Programs
You do not have to cross the finish line entirely on your own. Thousands of assistance resources exist across the country to help buyers bridge the gap.
Data from Down Payment Resource reveals that more than 2,500 homebuyer assistance programs operate nationwide, with roughly 60% to 65% dedicated to first-time buyers.² Many people assume these programs are strictly for very-low-income households, but that is not the case. Over 60% of available assistance programs have income limits that exceed $100,000, and some programs have no income limits at all depending on the location of the home.²
These programs usually take a few different forms
• Outright grants: These provide cash gifts toward your down payment or closing costs that you never have to pay back.
• Forgivable second mortgages: These zero-interest loans require no monthly payments and are completely forgiven if you stay in the home for a set period, typically five years.
• Low-down-payment conventional loans: Options like Fannie Mae's HomeReady and Freddie Mac's Home Possible let qualified buyers purchase with just 3% down.
• Government-backed loans: FHA loans require 3.5% down with flexible credit score requirements, while VA and USDA loans offer 0% down options for eligible military veterans and rural home buyers.
Check with local housing finance agencies and regional lenders to see what programs operate in your target county. Getting a $5,000 or $10,000 assistance grant can cut your personal savings timeline in half.
Boost Your Progress and Accelerate Your Savings
Consistency does the heavy lifting, but occasional cash injections can provide a massive psychological boost. When you see your balance jump significantly in a single day, sticking to your plan becomes much easier.
Make a personal rule that every financial windfall goes straight into your down payment fund. This includes tax refunds, annual performance bonuses, holiday cash, and birthday checks. If you receive an average tax refund of $2,500, dedicating that entire check to your home fund covers a substantial portion of a minimum down payment on an entry-level home.
Another smart tactic is using the raise escalator. Whenever you get a merit raise or cost-of-living bump at work, immediately increase your automated savings transfer by that exact amount. Since you were already living on your previous income, you will not miss the extra cash.
You can also test out short-term side hustles to generate extra savings power. Selling unwanted furniture, picking up freelance assignments, or working a weekend shift for six months can easily generate $300 to $600 in extra monthly savings. Channeling that side money exclusively toward your down payment will help you reach closing day much faster than relying on your day job alone.
Sources:
1. First-Time Home Buyer Share Inches Up to 22%, Median Age Remains at Record High of 40
https://www.nar.realtor/newsroom/first-time-home-buyer-share-inches-up-to-22-median-age-remains-at-record-high-of-40
2. 2025 Kicks Off with Record Number of Homebuyer Assistance Programs
https://downpaymentresource.com/professional-resource/2025-kicks-off-with-record-number-of-homebuyer-assistance-programs/
*This article on Katiently is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*
 Basics- How to Get the Full Employer Match -2.jpg)