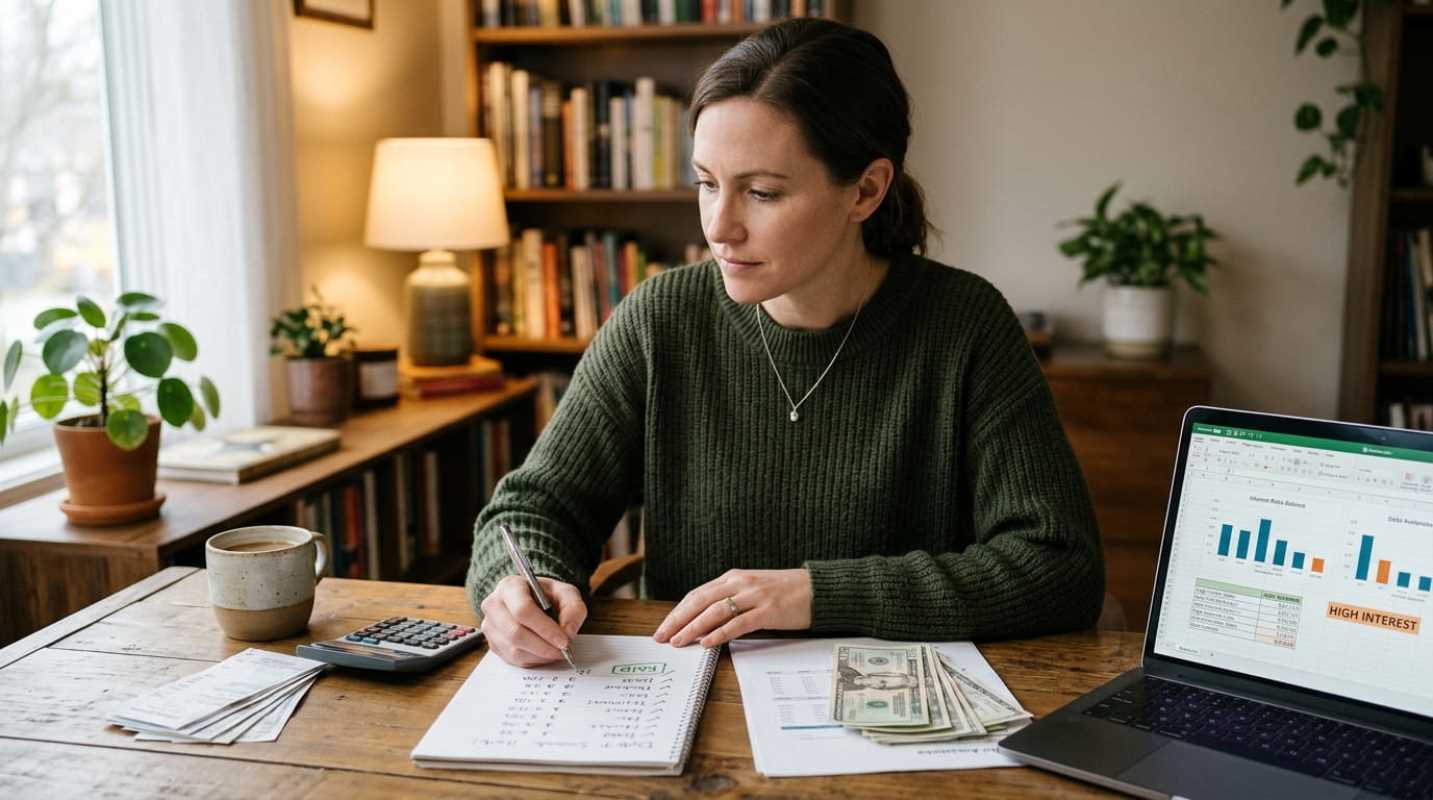
Owing money is exhausting. When you open your banking app and see balances spread across cards, student loans, and a car note, the sheer noise can freeze you in place. You want out, but you need a clear path forward.
That brings us to the classic personal finance showdown. On one side stands the Debt Snowball, which tells you to knock out your smallest balances first to build momentum. On the other side sits the Debt Avalanche, which insists you tackle your highest interest rates to save money.
So what does this actually mean for your wallet? The right choice comes down to how your brain handles motivation versus how much money you lose to interest along the way. Both methods work, but they work on completely different principles.
The Debt Snowball and Psychological Wins
The Debt Snowball keeps things simple. You list all of your debts from the smallest balance to the largest, ignoring the interest rates entirely. You pay the minimum on everything except the smallest account, throwing every spare dollar at that single tiny balance until it hits zero. Once it's gone, you roll that entire payment into the next smallest balance.
Why would anyone ignore math like this? Because humans are not spreadsheets.
When you eliminate an entire account in sixty days, your brain gets an instant dopamine hit. Behavioral researchers have studied this exact reaction. In a study published in the Journal of Marketing Research, researchers Gal and McShane analyzed roughly 6,000 debt settlement accounts.¹ They discovered that the total number of accounts closed was the single strongest predictor of whether someone actually crossed the finish line.
Getting rid of a $400 retail card feels amazing. It gives you immediate proof that your budget works. Psychologists call this the fractional elimination effect. When you wipe out 100% of an account balance, your perceived ability to succeed skyrockets. Knocking out three small accounts in four months eliminates mental clutter, frees up individual minimum payments, and keeps you from throwing your hands up in defeat.
The Debt Avalanche as the Mathematical Powerhouse
The Debt Avalanche takes an entirely analytical approach. You list all of your balances in order of interest rate (APR), from highest to lowest, regardless of the balance size. You make minimum payments on everything, and you direct every spare dollar toward the loan with the nastiest interest rate.
This method minimizes the total cash you hand over to banks. When you carry credit card balances at 22% or 24%, compounding interest is actively working against your future. Paying down that high-rate balance first is the financial equivalent of getting a guaranteed 24% return on your money.
Economist Ben Hamilton modeled this trade-off using data from the Federal Reserve's Survey of Consumer Finances.² His research revealed that for roughly 40% of households, the two methods perform about the same because their smallest balance also happens to have a high APR. But for the remaining 60%, sticking strictly to the Snowball costs borrowers between 1.8% and 4.3% more in total interest.
In low-rate times, that percentage gap might only mean a few extra dinners out. But in 2026, with credit card interest rates hovering near record highs and consumer delinquency rates climbing, that spread matters. LendingTree modeled wide-spread scenarios where credit card debt sits at 24% while auto or student debt sits at 6%. In those setups, the Avalanche saved borrowers over $2,000 in interest and cut three to six months off their total repayment time.³
Comparing Payoff Orders to Fit Your Life
Choosing between these approaches comes down to an honest look at your personal habits and your debt spread.
Here is how the two methods line up in practice
• Primary focus: Snowball targets the lowest balance first, while Avalanche targets the highest APR first.
• Interest paid: Snowball costs more over time, while Avalanche guarantees the lowest total interest expense.
• Speed to first victory: Snowball delivers an account closure in one to three months, while Avalanche can take a year or longer if your highest-APR balance is large.
• Mental friction: Snowball builds early motivation and clears billing clutter quickly, while Avalanche requires patience before you see an account balance hit zero.
• Ideal candidate: Snowball fits anyone feeling overwhelmed by multiple monthly payments, while Avalanche fits analytical individuals who hate wasting a single dollar on interest charges.
What if you want the best of both worlds? Many financial planners recommend a hybrid approach. You take your one or two smallest nuisance debts under $1,000 and destroy them using the Snowball method. Once you have cleared those accounts and freed up monthly cash flow, you flip straight into the Avalanche method to attack the remaining balances by highest APR. You get the early emotional win without letting 24% credit cards bleed you dry for three years.
Approaches for Staying Motivated Regardless of Method
A repayment plan looks great on paper, but everyday life gets in the way. Your car needs a water pump, or your hours get trimmed at work. Staying on track requires a few practical habits
• Track progress visually: Put a simple chart on your fridge or use a visual tracking app. Watching a bar fill up as your balance drops keeps your brain engaged during the long middle stretch.
• Automate your baseline: Set every minimum payment on autopay for the day after your paycheck hits. This avoids missed payments and late fees.
• Bank your freed-up minimums: When an account reaches zero, do not absorb that extra cash back into your grocery or entertainment budget. Roll the exact minimum payment into your next target immediately.
• Allow yourself to switch: If you start with the Avalanche method and feel burned out after eight months of grinding on a giant credit card balance, pivot to the Snowball. Knocking out an easy balance is far better than giving up entirely.
The best approach is simply the one you stick to for the next two years.
Choosing Your Path to Being Debt Free
Do not spend the next three weeks agonizing over spreadsheets, trying to decide whether the Snowball or the Avalanche is mathematically superior for your situation.
If you feel anxious, overwhelmed, and tired of keeping track of seven different monthly bills, choose the Debt Snowball. Knocking off a couple of small balances will give you immediate relief and the confidence to keep going. If you love spreadsheets, hate bank fees, and have the patience to grind through a large balance without losing focus, pick the Debt Avalanche and pocket the interest savings.
Line up your statements, pick your order today, and throw your first extra payment at the top debt on your list. Action creates clarity.
Sources:
1. Journal of Marketing Research (Account Closure Study)
https://www.nber.org/system/files/working_papers/w20125/w20125.pdf
2. Southern Economic Journal (Hamilton Econometric Analysis)
https://ideas.repec.org/a/wly/soecon/v89y2023i3p830-859.html
3. LendingTree Debt Payoff Simulation
https://www.lendingtree.com/debt-consolidation/debt-avalanche-snowball-study/
*This article on Katiently is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*
 Basics- How to Get the Full Employer Match -2.jpg)