When a marriage is ending, your first instinct might be to sprint to the courthouse and get it over with. You want closure, and you want it yesterday. But rushing into a divorce without a clear legal and financial plan is one of the most expensive mistakes you can make.
Taking a beat to prepare behind the scenes changes everything. It puts you in control of your timeline, protects your assets, and keeps your stress levels from boiling over once the legal process officially kicks off.
The Power of Preparation and Why You Should Never Rush a Divorce
Have you ever tried packing for a cross-country move thirty minutes before the moving truck arrives? You forget things, break valuables, and end up paying triple for emergency help. Rushing into a divorce feels the same way.
When you take the time to prepare before filing, you shift from playing defense to playing offense. You can quietly gather records, assess your living expenses, and build a game plan without the ticking clock of court deadlines hanging over your head.
There is also a persistent myth that the spouse who files first automatically wins. In most family courts, that is simply not true. Judges do not give bonus points for filing first. Aside from a few minor procedural details, like who presents their case first at a hearing, filing first gives you zero substantive legal edge regarding asset division or child custody.
What actually gives you an edge is readiness. Walking into the process with your paperwork in order, your immediate cash flow secured, and a clear understanding of your state laws will do far more for your future than racing to file a petition on a whim.
Mastering Your Money and Gathering Financial Documents
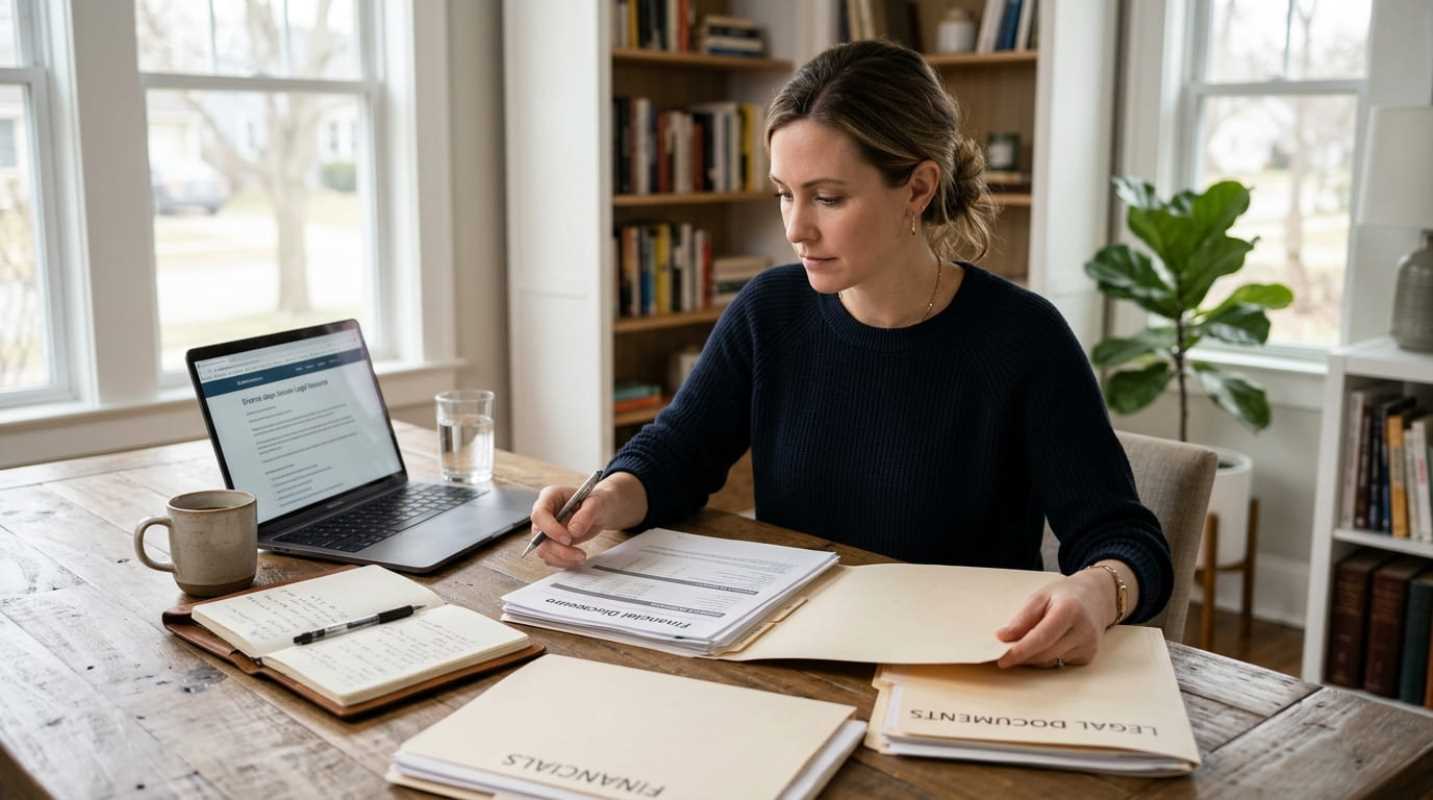
Divorce is largely a financial transaction. The court cannot divide what it cannot see, which means you need a complete picture of your household balance sheet before anything gets filed.
Family law attorneys often note that walking into an initial consultation with your documents already organized can save you anywhere from $500 to $2,000 in early billable legal fees.¹ When your lawyer has to spend hours tracking down missing statements, your retainer disappears fast.
Before you file, pull together records across these key areas
• Income and Earnings: Collect federal and state tax returns for the past three to five years, including all W-2s, 1099s, and K-1 schedules. Grab pay stubs for both spouses covering the last three to six months, along with documentation of any bonuses or commissions.
• Banking and Cash Accounts: Download six to twelve months of statements for all checking, savings, and certificate of deposit accounts. Do not forget digital payment histories from apps like Venmo, PayPal, and Zelle.
• Retirement and Investments: Gather the most recent statements for 401(k)s, IRAs, pensions, and brokerage accounts. If either of you holds restricted stock units (RSUs) or stock options, pull the grant letters and vesting schedules.
• Debts and Liabilities: Pull statements for every credit card, auto loan, student loan, and personal line of credit. You need to know what you owe just as clearly as what you own.
• Real Estate and Personal Property: Track down mortgage statements, tax assessments, purchase deeds, and recent appraisals.
• Digital and Complex Assets: If you or your spouse hold cryptocurrency, document the exchange accounts, public wallet addresses, and hardware wallets. For business owners, collect three to five years of profit-and-loss statements, balance sheets, and corporate tax filings.
Honesty is your best legal shield here. Hiding assets or shifting money around right before filing will backfire. If a judge catches you playing shell games with marital funds, you risk severe court sanctions, paying your spouse's legal fees, and losing your share of the hidden asset.
Understanding Property Division and What Belongs to Whom
Before you start dividing the household, you need to understand how your jurisdiction views ownership.
States handle property division under two main frameworks: community property and equitable distribution. In community property states like California, Texas, and Washington, assets and debts acquired during the marriage are typically split right down the middle, fifty-fifty. In equitable distribution states, which make up the majority of the country, courts divide marital property based on what is fair, which does not always mean equal.
To handle this, you must separate your assets into two distinct buckets
• Separate Property: This generally includes assets you owned before the marriage, inheritances left specifically to you, and personal gifts.
• Marital Property: This includes virtually all income, property, retirement contributions, and debts accumulated by either spouse during the marriage, regardless of whose name is on the title.
The danger zone is commingling. If you put an inheritance into a joint bank account to pay for a kitchen remodel, that separate asset likely morphed into marital property. Getting an early appraisal on real estate, art collections, or family businesses prevents common property undervaluation traps that leave you shortchanged later.
Choosing a Path Between Mediation and Litigation
How your divorce unfolds depends heavily on the dispute resolution path you choose. You do not have to fight it out in a courtroom. In fact, most couples benefit from avoiding a judge altogether.
Mediation uses a neutral third-party facilitator to help you and your spouse negotiate a binding settlement. Litigation relies on two opposing attorneys battling through formal court motions, depositions, and a public trial.
The differences in cost and timeline are staggering
• Total Cost: Household expenses for mediation typically run between $3,000 and $8,000 in total.² Contested litigation, on the other hand, frequently costs each spouse $15,000 to $30,000, easily pushing total household legal fees past $60,000.
• Resolution Timeline: Mediated divorces usually wrap up in two to six months. Litigated divorces routinely drag on for twelve to twenty-four months due to crowded court dockets.
• Privacy and Control: Mediation keeps your personal disagreements and sensitive financial records completely private. Litigation enters your disputes, tax documents, and parenting squabbles into the public court record.
Mediation works best when both partners are willing to share information openly and treat each other fairly. But if your marriage involves hidden assets, complex fraud, or domestic abuse, litigation provides the formal subpoena power and protective court orders necessary to keep you safe and make sure an honest accounting.
Building Your Support Team and Finalizing Your Approach
Your pre-filing approach requires a trusted group of advisors. Look for an attorney or mediator who focuses exclusively on family law. Meeting with two or three professionals before committing helps you find someone whose communication style matches your goals.
As fellows of the American Academy of Matrimonial Lawyers often point out, early legal groundwork protects both your parental standing and your marital estate before the legal machinery takes over.³
Take these practical protection steps before your spouse receives the initial paperwork
• Open Independent Accounts: Set up a new checking and savings account in your name alone at a bank your spouse does not use. Get a separate credit card to protect your credit score. Never drain existing joint accounts, because doing so can lead to judicial penalties for asset dissipation.
• Lock Down Digital Privacy: Create a fresh, secure email address dedicated solely to legal discussions. Change your passwords, PINs, and two-factor authentication on personal devices, cloud storage, and social accounts. Check your phone plan to make sure location sharing is turned off.
• Verify Residency Requirements: Confirm that you meet your state residency rules, which usually require three to six months of continuous living in the state and thirty to ninety days in the county where you plan to file.
• Understand Restraining Orders: In many states, filing a petition immediately triggers Automatic Temporary Restraining Orders. These orders freeze marital assets, stop you from changing insurance beneficiaries, and forbid moving minor children across state lines without written consent.
Taking these steps today gives you the space to think clearly, negotiate from a position of strength, and step into your next chapter with your finances and dignity intact.
Sources:
1. Foley Family Law
https://wfoleylaw.com/what-to-bring-to-divorce-consultation/
2. Real Cost Report
https://www.realcostreport.com/legal/family-law-divorce/mediation-vs-litigation-cost/
3. American Academy of Matrimonial Lawyers
https://www.aaml.org/resources/aaml-journal/
*This article on Katiently is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*